File ECI and your corporate tax return yourself
Prepare the year-of-assessment computation from the ledger, check Form C-S eligibility, file ECI within 3 months of year end and the return by 30 November.
Who can do this
Finance operator prepares; a director-level approver reviews
Primary route
/finance/tax
Last verified
5 August 2026
- A closed or near-final financial year in Finance
- The entity’s financial year end recorded in Finance settings
- Corppass access to myTax Portal (Corporate Tax) for the submitter
01
Know the two filings and their clocks
Corporate income tax is two separate acts each year of assessment (YA): the Estimated Chargeable Income (ECI) filing within 3 months after the financial year end, and the income tax return (Form C-S, C-S Lite, or C) by 30 November. The YA is the calendar year following your financial year end.
- ECI waiver: no filing is needed if annual revenue is S$5 million or below AND the ECI is nil — both conditions must hold.
- Filing ECI early preserves the option of paying the assessed tax by interest-free monthly instalments under GIRO; later filing shortens or removes the instalment plan.
- Singapore taxes at a flat 17% with partial exemption on the first S$200,000 of normal chargeable income.
02
Prepare the computation in the Tax Workspace
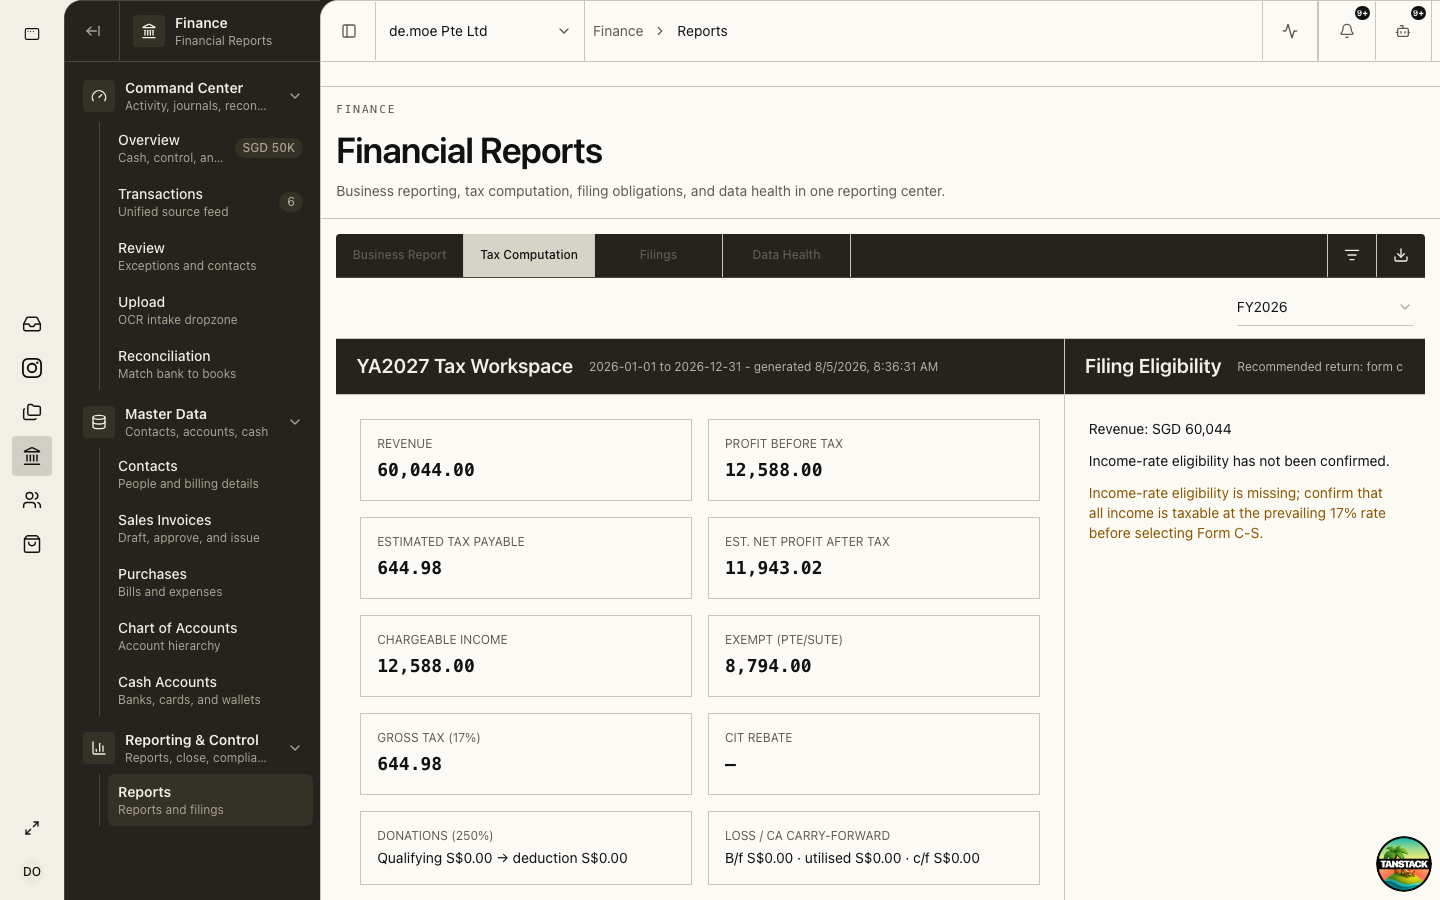
Finance → Reports → Tax Computation builds the YA tax workspace from your posted ledger: revenue, profit before tax, add-backs, capital allowances, enhanced deductions, exempt income, and loss carry-forward positions, down to estimated tax payable.
- Select the entity and financial year; the YA workspace generates from the closed ledger.
- Review Add-backs: non-deductible items (depreciation, private expenses, fines) are reversed out of accounting profit.
- Review Capital allowances claimed in place of depreciation on qualifying assets.
- Confirm enhanced deductions and exempt income adjustments against their supporting schedules.
- Check the Filing Eligibility panel: it recommends Form C-S, C-S (Lite), or Form C and lists any unconfirmed eligibility facts.
Group relief, foreign tax credit, double-tax treaty relief, and carry-back claims are outside Form C-S and outside the platform’s prepared schedules — take professional advice for those positions and file Form C.
Expected result: A chargeable-income computation you can trace from accounting profit to tax payable.
03
File ECI, then the return
Both filings happen in myTax Portal with Corppass, or through the connected IRAS API where enabled. Form C-S is a short return for qualifying companies: Singapore-incorporated, revenue S$5 million or below, income taxed at 17%, and not claiming the excluded reliefs; C-S (Lite) further requires revenue S$200,000 or below.
- File ECI within 3 months of year end unless the waiver applies; use the platform computation, not a guess — a lowballed ECI followed by a much higher return invites queries.
- Track both obligations in Finance → Reports → Filings; Prepare builds the filing draft and validates it against the computation.
- Submit through the connected API via Request submission, or file in myTax Portal and mark the row manually filed with the acknowledgement attached.
- Pay the Notice of Assessment within 1 month, or let the GIRO instalment plan run.
- Record the NOA against the filing and reconcile the tax expense and provision in the ledger.
04
Keep the trail IRAS expects
Self-filing is fully accepted; what matters is that the computation is supportable when queried.
- Retain the computation version, source schedules, filed return, acknowledgement, and NOA together on the filing record.
- Records must be kept for at least 5 years from the relevant YA.
- If IRAS raises a query, answer from the platform’s schedules and documents — that is exactly what they are for.
Troubleshooting
- Eligibility panel says Form C: one of the C-S conditions failed (revenue, excluded claims, or income taxed other than 17%) — file the full return with financial statements and computation attached.
- ECI deadline passed without filing: file immediately; IRAS may issue its own estimated assessment, which is harder to displace than a filed ECI.
- The computation disagrees with your accountant’s: compare the add-back and allowance schedules line by line — the discrepancy is almost always in one of those two.